The Money Edit
Your Emergency Fund, Without the Panic — What a Financial Buffer Is Really For
What is an emergency fund really for? A calm guide to financial buffers, unexpected expenses, savings targets and why there is no single magic number.
Saving, Beautifully · 15 min read
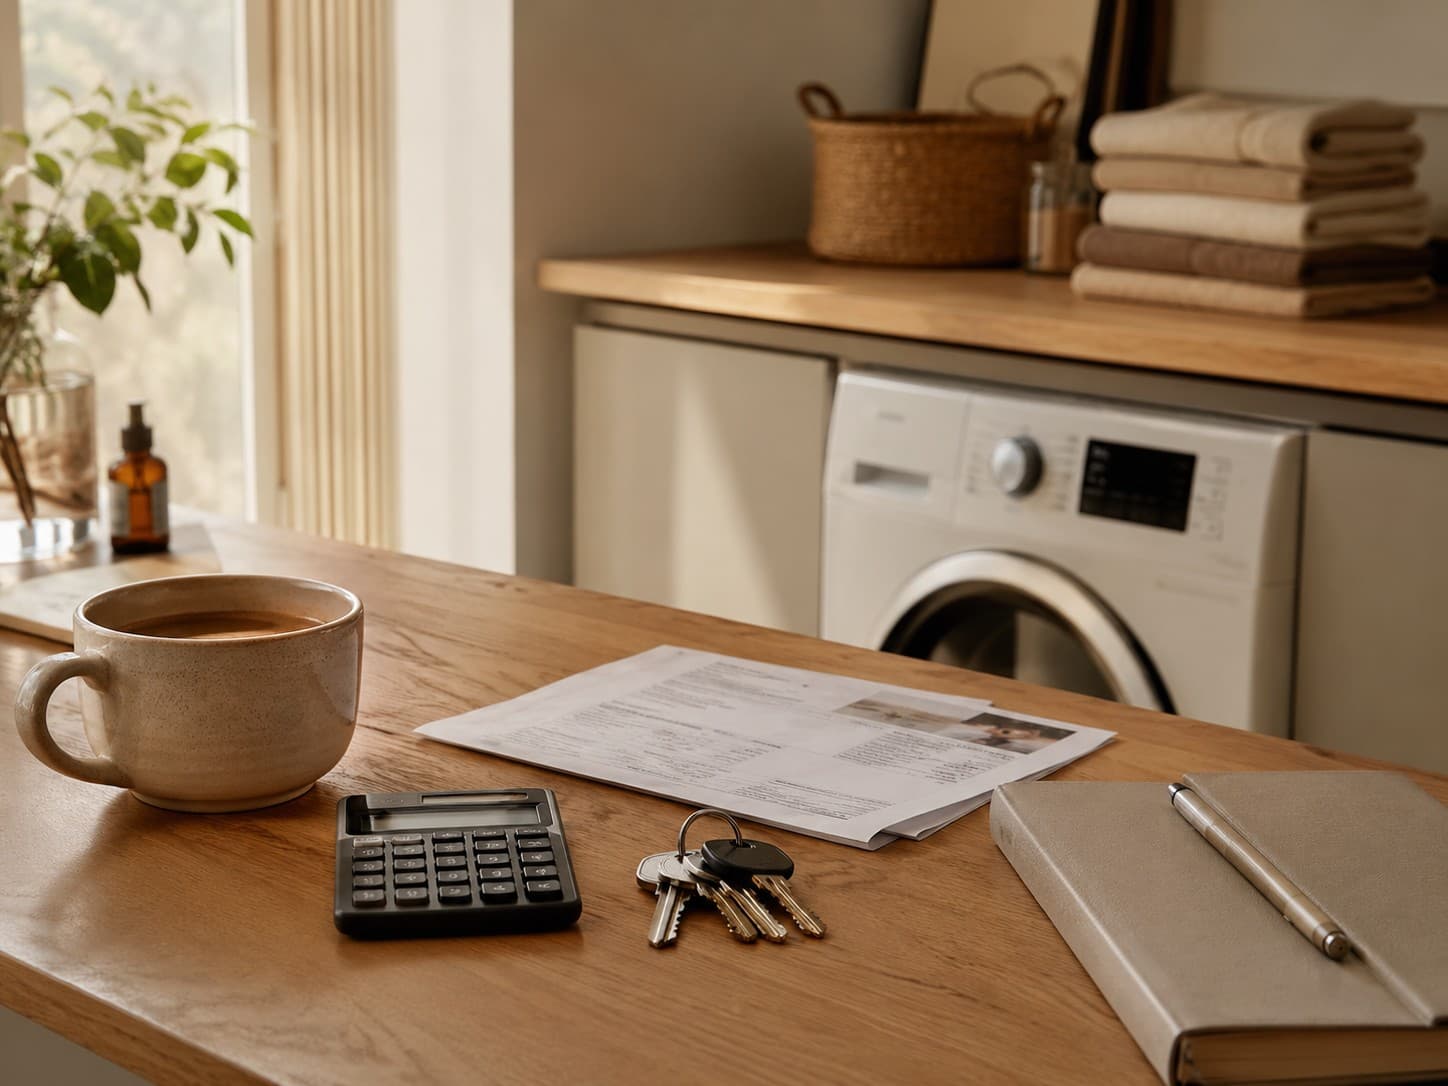
“The buffer is what protects the rest of your financial life.”
Of everything I save for, my emergency fund is the least glamorous and the most important.
There is no exciting graph attached to it. No lovely purchase waiting at the end. No trip to plan around it.
It simply sits there, quietly, doing one job: making sure that when something goes wrong, it stays an inconvenience instead of becoming a crisis.
And yet, whenever I mention it, I notice how much anxiety the topic seems to carry for a lot of people. How much is "enough"? Am I behind? Should I already have six months of expenses sitting in an account somewhere?
So I want to talk about it properly - without the panic, and without a single magic number pretending to apply to everyone.
An emergency fund is not the same as savings in general
This is where I think a lot of the anxiety starts. People treat "savings" as one big undifferentiated pile, and then feel behind because that pile is not large enough to cover every possible thing that might ever happen.
An emergency fund is not your entire financial life. It is one specific pot, with one specific job: covering costs that are unexpected, necessary and cannot reasonably wait.
A car repair. A boiler that stops working in December. An unexpected medical cost. A sudden gap in income.
It is not your holiday fund. It is not your home renovation fund. It is not the account you dip into because something lovely went on sale. Those things matter too, but they have their own pots, and I write about how I organise those separately, elsewhere in The Money Edit.
What counts as an actual emergency
I find it helpful to be quite strict with myself here, because "emergency" can quietly expand to cover things that are really just unplanned spending.
A genuine emergency tends to have three features: it is necessary, not optional; it is unexpected, or at least unexpected in its exact timing; and it cannot reasonably be delayed until the next time I would normally save for it.
A broken washing machine, yes.
A spontaneous weekend away because a flight was cheap, no - lovely, but not an emergency.
A sudden essential home repair, yes.
Wanting to buy something before a sale ends, no, however convincing it feels in the moment.
This distinction keeps the fund doing its actual job.
How much is actually enough?
This is the question I get asked most, and I want to be honest: there is no single correct number, however satisfying a tidy answer would be.
Nibud, the Dutch National Institute for Family Finance Information, offers a calculator - the BufferBerekenaar - that estimates a sensible buffer based on your own household situation, rather than applying one flat figure to everyone. It is a genuinely useful starting point if you live in the Netherlands. If you live elsewhere, the specific Dutch figures will not directly apply, but the underlying approach - basing your target on your own household’s real circumstances rather than a number borrowed from somewhere else - is a good principle wherever you live, and it is worth checking whether a similar tool exists from a consumer-finance body or regulator in your own country.
More broadly, the amount that makes sense for you depends on things like: how stable your income is, whether you have dependents, whether you own or rent your home, how old your appliances and car are, and simply how much financial stress keeps you up at night versus how much you can comfortably sit with.
A freelancer with irregular income and a single-income household with young children are not the same situation, even if their monthly expenses happen to look similar on paper.
I would rather you calculate a number that fits your actual life than borrow mine.
Why I built mine before I did anything else with my money
Before I started thinking seriously about investing, before I got particular about lovely, non-essential purchases, I built this fund first.
Not because it is the most interesting part of managing money. It genuinely is not.
But because it is the part that protects everything else.
Without a buffer, an unexpected expense does not just cost money. It costs your other plans. It pulls from the holiday fund, or worse, from money that was invested and would now have to be sold, potentially at an inconvenient moment, simply to cover something that should have had its own pot from the start.
I wrote, elsewhere in The Money Edit, about why I think investing and saving are not the same job. This is a large part of why: investing is for money you will not need on short notice. An emergency fund exists precisely so that an unexpected expense never forces that question.
Where I actually keep it
My emergency fund lives in an easily accessible savings account - not invested, not locked away somewhere that takes days or weeks to reach.
The whole point of this money is that it needs to be there when something goes wrong, not three business days later, and not at whatever value the market happens to be offering that week.
It earns very little interest sitting there, and I have made peace with that. This is not the pot where I am trying to grow money. It is the pot where I am trying to protect everything else.
Building it slowly is still building it
If you are starting from very little, or from nothing, I want to say clearly: that is a completely normal place to begin.
A buffer does not need to appear all at once. Mine did not. It grew slowly, through a consistent, modest monthly amount, the same way the rest of my savings pots did.
A small buffer is still meaningfully better than no buffer. €200 set aside is €200 that does not need to go on a credit card the next time something breaks. It does not need to be a perfect number to be a useful one.
Progress here counts, even when it is slow.
Can a financial buffer be too big?
Most of what I hear about emergency funds is the worry of not having enough. But every so often, someone asks me the opposite: "I think mine might be too big. Is that actually fine?"
It usually is. A generous buffer is not a mistake.
But it is worth revisiting every so often, the same way I revisit my savings pots. Money that has sat untouched in a low-interest account for years, well beyond anything a realistic emergency could ever need, is not doing very much for you sitting there. It might genuinely have a better job elsewhere - as something invested for the longer term, or funding something you have actually been wanting.
There is no failure in either direction. If a larger number helps you sleep at night, that peace of mind is worth something too - a small, deliberate premium for feeling calm is a perfectly reasonable financial choice. The only real question is whether the size of your buffer is still a decision, or whether it has simply become a habit nobody has looked at in years.
What happens once the fund gets used
At some point, something will happen, and the fund will do exactly what it was built for.
When that happens, I try to treat it as the system working correctly, not as a setback. That is the entire purpose of having built it.
The only step after that is refilling it, at the same steady pace it was built the first time. It does not need to be replaced overnight. It simply needs to go back on the list.
Why this belongs in a beautifully organised life
I think a financial buffer is one of the least visible forms of self-care.
It does not photograph well. Nobody plans a cosy evening around their emergency fund.
But it is quietly responsible for a huge amount of the calm that shows up everywhere else. The ability to handle a broken appliance without panic. The freedom to make an investing decision from a place of stability rather than fear. The peace of knowing that one unlucky week will not undo months of careful planning.
The buffer is what protects the rest of your financial life.
That is worth building, even without the glamour.
Common Questions About Emergency Funds
How much should be in an emergency fund?
The most commonly cited starting point is three to six months of essential expenses - rent or mortgage, utilities, groceries, insurance and minimum debt payments, not your full lifestyle spending. Where you land in that range, or outside it, depends on how stable your income is, whether you have dependents, and how much financial stress you can comfortably sit with. See "How much is actually enough?" above for how to calculate a number that fits your own situation rather than borrowing this one.
Is a small amount, like €1,000, enough for an emergency fund?
It is not the widely cited target, but it is a genuinely useful starting buffer, and far better than nothing. A small fund still covers many common emergencies - a car repair, a broken appliance - without going on a credit card. Build from there rather than waiting until you can fund the full three to six months in one go.
Should I build my emergency fund before I start investing?
Yes. An emergency fund is money you may need on short notice, and investments are for money you will not need for years - mixing the two means an unexpected expense could force you to sell investments at an inconvenient moment. Build the buffer first, then invest what is left over.
Where should an emergency fund be kept?
Somewhere easily accessible - a standard savings account, not invested and not locked away in anything that takes days or weeks to reach. The interest earned matters far less than being able to get to the money immediately when something goes wrong.
What is "buffer money"?
"Buffer money" and "financial buffer" describe the same thing as an emergency fund - a separate, easily accessible pot of savings set aside for genuine unexpected expenses, kept apart from everyday spending and from savings pots earmarked for something else. Different people simply use different words for it; this entire article is about that one pot.
Editor’s Note
I deliberately have not shared the exact number I keep in my own emergency fund in this piece. The right amount is genuinely personal, and I would rather you calculate one that fits your own life than anchor to mine.
A Small but Important Disclaimer
This article shares general information and personal experience about emergency funds and financial buffers for educational and editorial purposes. It is not personal financial advice.
The right size for your own emergency fund depends on your income, expenses, household and circumstances. If you would like guidance tailored to your own situation, consider speaking with a qualified financial adviser in your own country.
Sources & Further Reading
- Nibud (Dutch National Institute for Family Finance Information) — BufferBerekenaar - financial buffer calculator
- Nibud (Dutch National Institute for Family Finance Information) — Over deze tool - methodology behind the BufferBerekenaar
- OECD — Financial education (OECD/INFE)
Continue The Money Edit
Written by Esther
Esther is a photographer and storyteller, and the founder of Essy's Essentials - a seasonal home for stories, rituals, recipes and everyday luxuries.
·
More about Esther →